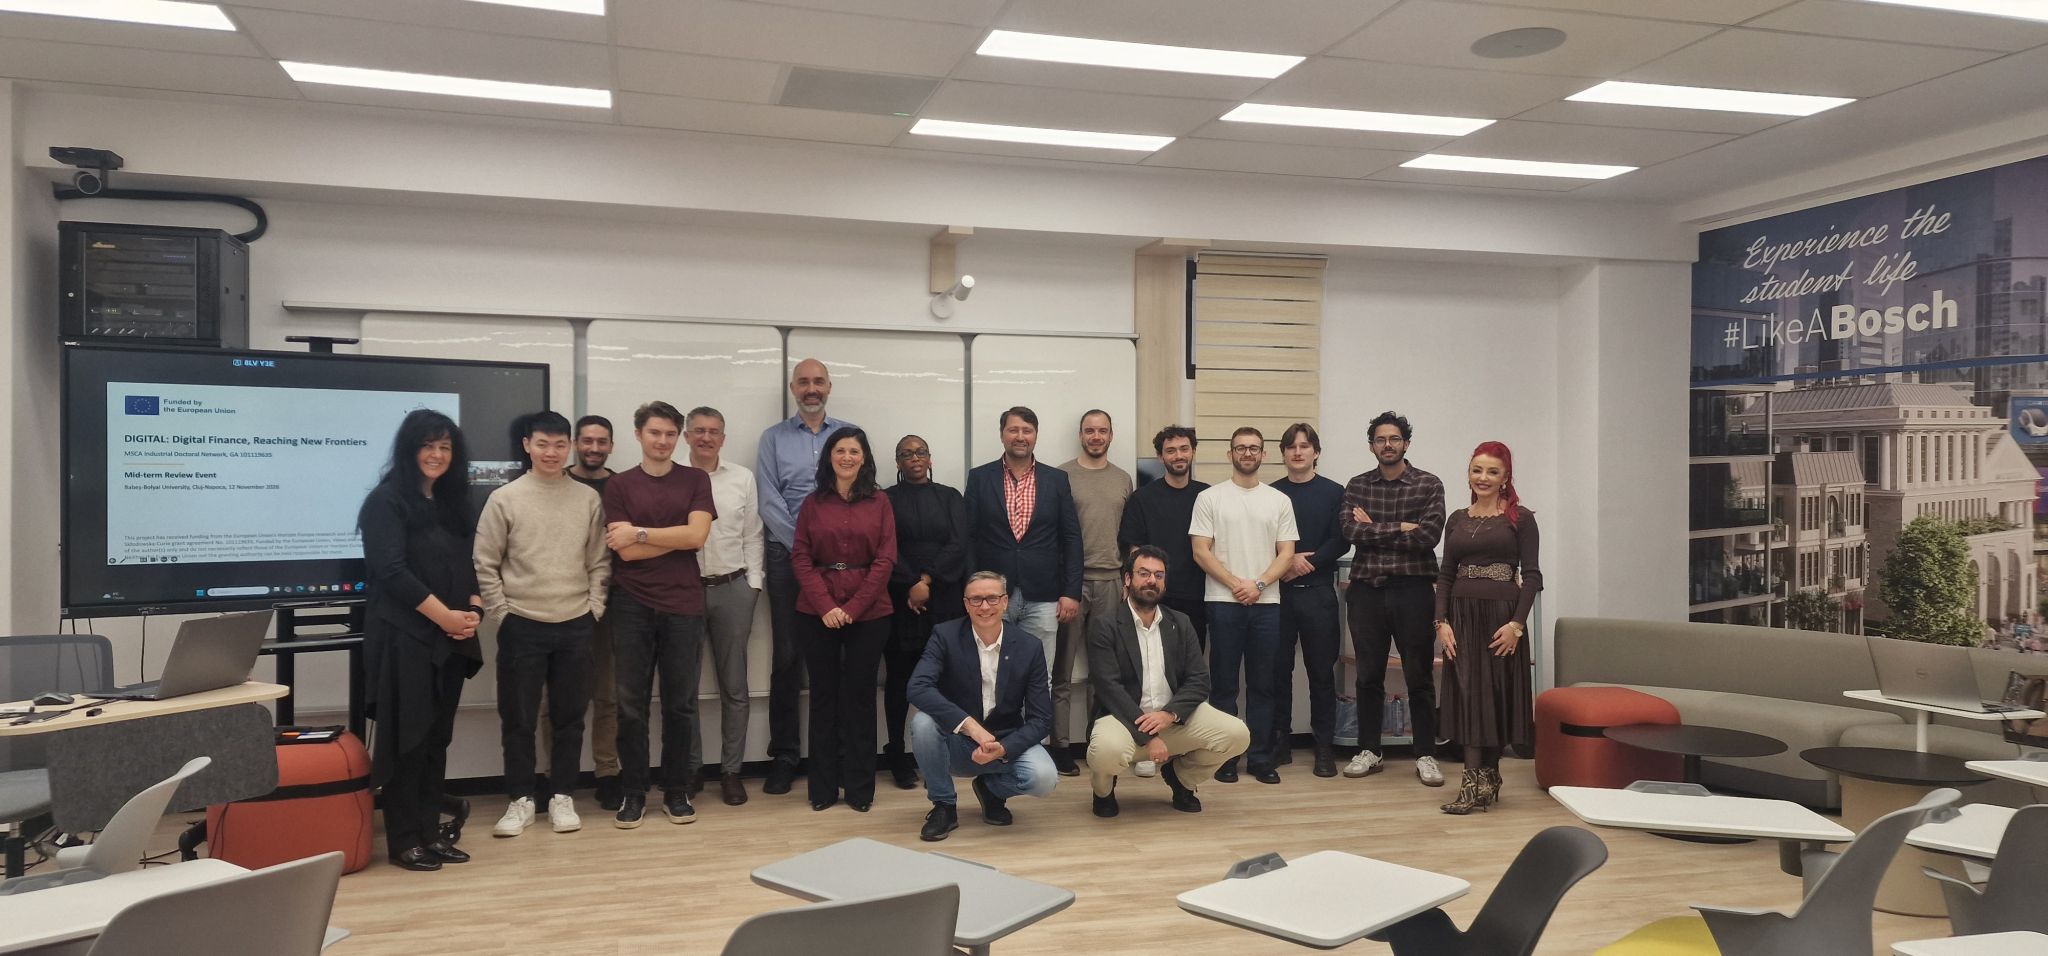
From 9 to 13 November 2026, Babeș-Bolyai University in Cluj-Napoca hosted a week of training and project review for the MSCA Digital Finance doctoral network, combining a training school on Anomaly Detection in Big Data with the network’s Mid-Term Event.
The first three days covered anomaly detection from fundamentals to financial applications. Data scientists from Dell Technologies led sessions on rare event detection, model interpretability and temporal anomalies in time series. Prof. Anastas Dzurovski presented on forecast accuracy and on anomaly detection in the S&P 500 using Isolation Forest and LSTM networks, while PhD student David Siang-Li Jheng introduced FINDER-LLM, a large language model approach to financial anomaly detection. Prof. Liana Stanca and Prof. Codruța Mare also led sessions.
On 12 November, Prof. Joerg Osterrieder opened the Mid-Term Event, where doctoral candidates, partners and work package leaders presented their progress and plans, and discussed the future of MSCA Digital. The week closed with sessions on data quality tools and data generation.
The event was organised by Prof. Codruța Mare, Prof. Monica Violeta Achim, Prof. Liana Stanca and third-year PhD student Fulvio Raddi.